Let's get you the best mortgage available

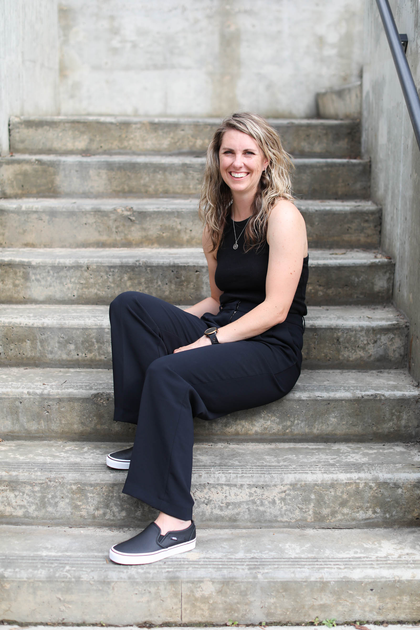
MARLIES ROMICH

MORTGAGE BROKER

Licensed in Alberta and B.C

GET STARTED

Finding the best mortgage can be frustrating. It doesn't have to be when you follow my 3 step plan.

Get started right away

The best place to start is to connect with me directly. My commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise. I'll outline the best mortgage products available with your needs in mind.

Proceed with confidence

My goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, I'm available to answer any questions for as long as you need a mortgage. I've got you covered.
Email: marlies@marliesromich.com

MARLIES ROMICH

Marlies Romich is a licensed Mortgage Broker serving clients in both British Columbia and Alberta. Currently based in the picturesque city of Cranbrook, BC, Marlies brings a relaxed yet professional approach to the world of mortgages.


Equipped to work digitally, in person, or in a hybrid fashion, she ensures convenience and flexibility for clients. With a keen eye for opportunities to save money throughout the lifespan of a mortgage, Marlies challenges the norm—when was the last time your bank proactively looked out for your financial interests?

Driven by a commitment to client satisfaction, Marlies focuses on ensuring that every mortgage not only meets but exceeds the needs of the client.


Whether you're a first-time homebuyer or a seasoned investor, she is dedicated to making your mortgage experience seamless and rewarding. Get in touch today and let Marlies help you unlock the full potential of your mortgage!

Get started by completing my online mortgage application.

APPLY NOW

I'll let you know exactly where you stand so you can proceed with confidence.

Let's run some numbers.

Start by telling us where you're at in your home buying journey.
Exciting times! Let's find out how much you'll be able to afford once you decide to buy.
I have a specific home in mind

Great! Let's find out whether you'll be able to afford to buy it!

I'd like to refinance

Everything you need, all in one place

As a trusted mortgage provider, let me help you with these services.

Click through any of the services to learn more
Mortgage articles to keep you informed.

By Marlies Romich September 15, 2026
Going Through a Separation? Here’s What You Need to Know About Your Mortgage Separation or divorce can be one of life’s most stressful transitions—and when real estate is involved, the financial side of things can get complicated fast. If you and your partner own a home together, figuring out what happens next with your mortgage is a critical step in moving forward. Here’s what you need to know: You’re Still Responsible for Mortgage Payments Even if your relationship changes, your obligation to your mortgage lender doesn’t. If your name is on the mortgage, you’re fully responsible for making sure payments continue. Missed payments can lead to penalties, damage your credit, or even put your home at risk of foreclosure. If you relied on your partner to handle payments during the relationship, now is the time to take a proactive role. Contact your lender directly to confirm everything is on track. Breaking or Changing Your Mortgage Comes With Costs Dividing your finances might mean refinancing, removing someone from the title, or selling the home. All of these options come with potential legal fees, appraisal costs, and mortgage penalties—especially if you’re mid-term with a fixed-rate mortgage. Before making any decisions, speak with your lender to get a clear picture of the potential costs. This info can be helpful when finalizing your separation agreement. Legal Status Affects Financing If you're applying for a new mortgage after a separation, lenders will want to see official documentation—like a signed separation agreement or divorce decree. These documents help the lender assess any ongoing financial obligations like child or spousal support, which may impact your ability to qualify. No paperwork yet? Expect delays and added scrutiny in the mortgage process until everything is finalized. Qualifying on One Income Can Be Tougher Many couples qualify for mortgages based on combined income. After a separation, your borrowing power may decrease if you're now applying solo. This can affect your ability to buy a new home or stay in the one you currently own. A mortgage professional can help you reassess your financial picture and identify options that make sense for your situation—whether that means buying on your own, co-signing with a family member, or exploring government programs. Buying Out Your Partner? You May Have Extra Flexibility In cases where one person wants to stay in the home, lenders may offer special flexibility. Unlike traditional refinancing, which typically caps borrowing at 80% of the home’s value, a “spousal buyout” may allow you to access up to 95%—making it easier to compensate your former partner and retain the home. This option is especially useful for families looking to minimize disruption for children or maintain community ties. You Don’t Have to Figure It Out Alone Separation is never simple—but with the right support, you can move forward with clarity and confidence. Whether you’re keeping the home, selling, or starting fresh, working with a mortgage professional can help you understand your options and create a strategy that aligns with your new goals. Let’s talk through your situation and explore the best path forward. I’m here to help.
By Marlies Romich September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
By Marlies Romich September 1, 2026
Why a Mortgage Pre-Approval Protects Both Your Head and Your Heart There’s no denying it—buying a home is an emotional journey. In a competitive market, it can feel like you need to stretch beyond your comfort zone or bid above asking just to have a chance. That pressure can make it hard to separate what you want from what you can realistically afford. One of the biggest pitfalls buyers face is falling in love with a home that’s outside their price range. Once that happens, every other property seems like a compromise—even the ones that might have been a perfect fit otherwise. The best way to avoid this heartache? Get pre-approved before you start shopping. What a Pre-Approval Does for You A mortgage pre-approval gives you more than just a number—it provides clarity, confidence, and protection: Know your buying power : Shop within your true price range and avoid disappointment. Spot potential roadblocks : Uncover issues like credit bureau errors before you make an offer. Get organized : Learn exactly what documentation you’ll need so there are no surprises. Lock in a rate : Many lenders hold your rate for 30–120 days, giving you peace of mind if rates rise. Save yourself heartache : Protect yourself from falling for a home you can’t afford. Head vs. Heart Buying a home is about balance. Your head tells you what’s financially sound, your heart tells you what feels right—and both matter. A pre-approval helps bring those two sides together, so you can make confident choices without emotional stress clouding your judgment. The Bottom Line Looking at properties for fun is one thing—but if you’re serious about buying, a pre-approval is the smartest first step you can take. It sets realistic expectations, saves time, and protects your emotions along the way. If you’d like to explore your options and get pre-approved, I’d be happy to walk through the process with you. Let’s make sure you’re ready to shop with confidence.